
Almost every electric tricycle enquiry that reaches a factory in Shenzhen follows the same arc. A distributor in Texas or a rental operator in Mallorca buys thirty units, runs them for one season, and discovers the hard part was never the vehicle. It was finding four more people in four more cities who would run the same operation to the same standard. That is the point at which an OEM customer stops asking for a better tricycle and starts asking for a channel program, and those are two different conversations.
The operator-layer model — a regional partner who buys or hosts units, runs them under a shared brand, and is measured on service metrics rather than inventory turnover — is what most mature micromobility categories eventually converge on. It differs from a straight dealership in one structural way: a dealer's success metric is units shipped out of the warehouse, and an operator's success metric is service revenue per vehicle per month, on a territory the supplier helped define. Every term in the agreement should follow from that difference.
This brief is written for channel builders and purchasing managers on both sides of that conversation: the distributor who wants to scale from one city to twelve, and the importer deciding whether to sell to an operator or sign one. Territory design, unit placement versus purchase, break-even maths, platform tiers and the commercial clauses that decide whether a network survives its second year are all covered below. Payload, battery, drivetrain and pricing figures are this manufacturer's own platform specifications.
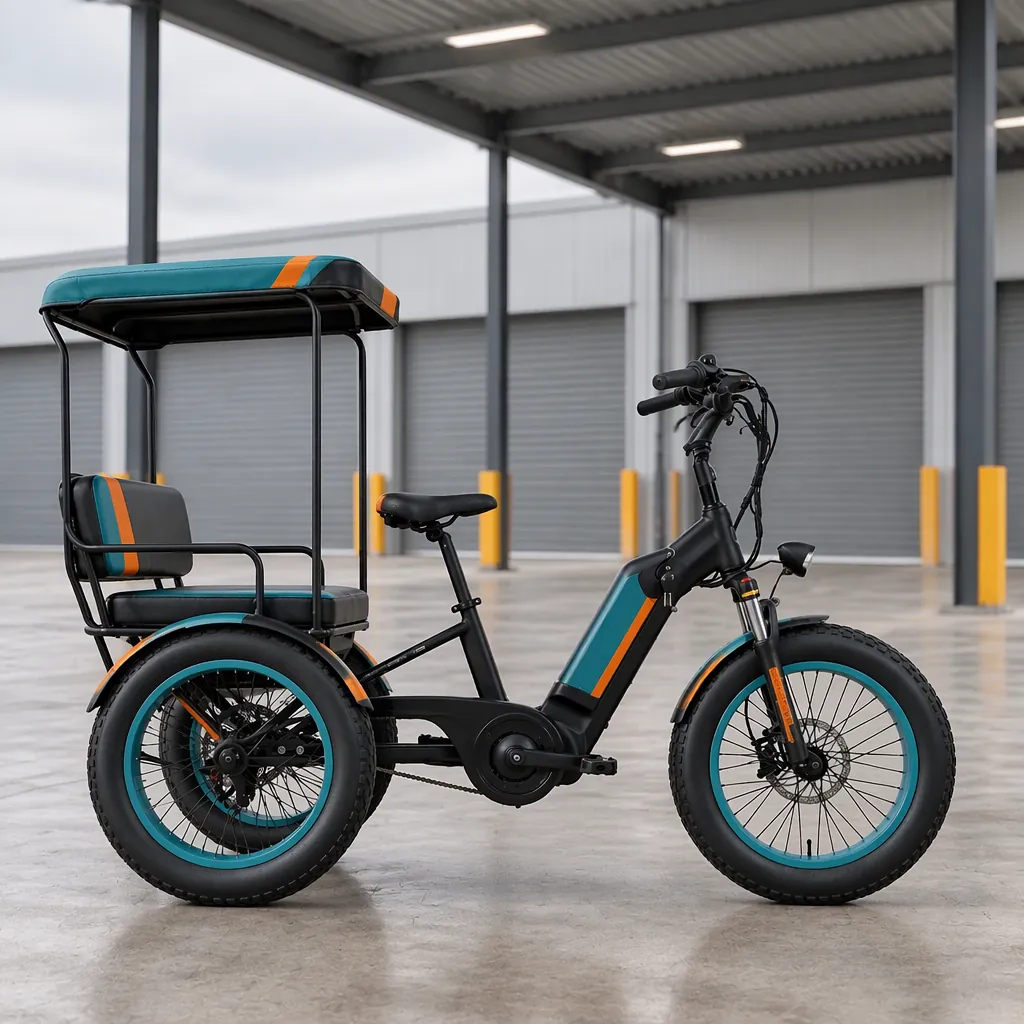
How the Operator Layer Differs From Dealership, Rentals and Shared Fleets
Four go-to-market structures are commonly confused because all four put vehicles into other people's hands. They carry very different obligations for the supplier, and a program written for one will fail when applied to another.
| Channel model | Who owns the asset | Supplier's core obligation | Revenue to the supplier |
|---|---|---|---|
| Dealership / distributor | The dealer, outright | Supply continuity, warranty, spares pipeline, margin protection | One-time unit margin, repeating parts |
| Operator franchise / district program | The operator, usually | Territory definition, brand standards, launch and service training, consumables | Initial fleet order plus ongoing spares and accessories |
| Rental concession | The operator, with brand licence | Specify a durable unit, guarantee seasonal resupply | Fleet orders, seasonal swing |
| Shared fleet (B2C) | The platform or the city | Volume supply, telemetry integration, damage economics | Large one-time deployments |
The distinction that catches suppliers out is the second column. When the operator owns the assets, the supplier's exposure ends at the invoice and the supplier has no basis for demanding service standards. When the supplier places the assets on a pay-per-use basis, the same units stay on a factory balance sheet for two to three years and the entire proposition becomes a financing and recovery problem, not a manufacturing one. Pick one, and write the agreement around it. Programs that drift between the two — placing some units and selling others under the same badge — reliably produce disputes about who pays for a battery that degrades faster than forecast.
Territory Design: The Clause That Decides Everything Downstream
A district is not a radius on a map. It is the smallest area in which one operator can hold a defined service standard with the vehicle type you are supplying. Get this wrong and the second operator you sign will be competing with the first inside a few months, which destroys unit economics for both and makes recruitment harder for every subsequent city.
Define a district by four measurable quantities rather than by city limits or postcodes.
- Service-area travel distance. How far the operator's recovery or swap van must travel from a base to reach the furthest authorised vehicle. With the fleet's 50–80 km working range at 200 kg on flat ground, a territory whose far edge is a 25 km drive from base is already at the practical limit for a single van and a single shift.
- Density, not population. Units per square kilometre matters more than headcount because it drives the number of stops a single service technician can complete in a day. Commercial districts, resort strips, industrial parks and university quarters all reach workable density at far lower populations than a low-density suburb does.
- Charging geography. Where the units can stand still for a 6–10 hour charge on a standard 5 A charger from a 230 V supply. If the territory has no lockable overnight location within it, the operator must build one, and that cost belongs in the territory decision, not in the operator's later complaint.
- Regulatory uniformity. A district should sit wholly inside one jurisdiction. Splitting a territory across a state or national boundary means two sets of speed limits, two sets of helmet and licensing rules and two ways of being inspected, which no small operator can hold.
Two practical sizing rules follow. First, a district should be small enough that the operator can walk or drive the whole territory in a day during launch, because in the first ninety days the job is reconnaissance, not sales. Second, it should be large enough to absorb the operator's minimum viable fleet without saturating demand — if a single operator's thirty units would cover 80 percent of the trips in the area you have drawn, the district is too small and there is no room for the fleet to grow before the operator's own units start cannibalising each other.
Buy, Place or Lease: Three Ways to Build the Fleet
The fleet-acquisition clause is where most operator programs are either made bankable or made impossible. There are three structurally different answers and each carries a different risk holder.
| Structure | Who funds the fleet | Supplier risk | Operator barrier | Best fit |
|---|---|---|---|---|
| Operator purchase | Operator, at order | Low — standard export terms apply | High — needs capital or credit before earning | Operators already in logistics, rental or property |
| Lease-to-operate | Third-party lessor or supplier-backed facility | Medium — depends on the lessor's underwriting | Low — monthly cost against monthly revenue | New operators without balance sheet |
| Placement / revenue share | Supplier or brand owner retains title | High — asset recovery, damage, repossession | Lowest — operator supplies labour only | Brand-led networks in high-density cities |
For most first-time channel programs the middle column is the right answer, and it is worth being explicit about why. The vehicles have a genuine second-hand market and a service life measured in years, so they are financeable assets — the same logic that underwrites fleet financing and leasing structures for direct fleet buyers. The platform-level order quantity of 50 units is high enough that a leasing partner will look at the order, and low enough that a first cohort of two to three operators can absorb it without a large facility. A placement model only makes sense once the brand, the app layer and the recovery process are proven, because until then the supplier is funding a fleet in a city it cannot police.
Operator Unit Economics: The Break-Even Territory
Operator programs fail for one reason more often than any other: the recruiting conversation was held in units per month when it should have been held in vehicle-hours per day. A prospective operator does not need to know how many tricycles you can ship; they need to know how many vehicles their local demand can keep occupied, and whether the fleet covers its own fixed costs before the operator's labour is paid.
Work the arithmetic in vehicle-hours. If a cargo tricycle config sells for $1,250–1,550 FOB in its base configuration, an operator landing it in a developed market typically carries a landed cost in the region of $1,900–2,400 after freight, duty, port handling and inland delivery, with heavier 1000 W differential builds at the upper end. Amortising that over a 30-month commercial life gives a capital cost per vehicle of roughly $63–80 per month before any financing charge. Add swap or spare batteries, a consumed-tires allowance, a maintenance reserve and insurance, and a single unit's all-in monthly cost before labour typically lands in the $110–165 range.
Now compare that against the revenue the operator can actually generate. A fleet duty cycle that keeps one tricycle occupied for five productive hours a day at a pricing level that produces $3–4 of gross hourly revenue covers that fixed cost with margin to spare on about 35–40 productive hours per month. That number is the recruitment threshold: if the operator's demand base cannot support roughly forty billable vehicle-hours per month for each unit they order, the fleet will not service its own debt, and no amount of branding will fix it.
The corollary is more useful than the threshold itself. Because the fixed cost is largely per-vehicle while revenue scales with hours, the model rewards concentrating units in one dense district far more than spreading the same number of units across several thin ones. Two thirty-unit districts will outperform three twenty-unit districts even though the total fleet is identical, which is also why the territory clause further up this page is not a formality.
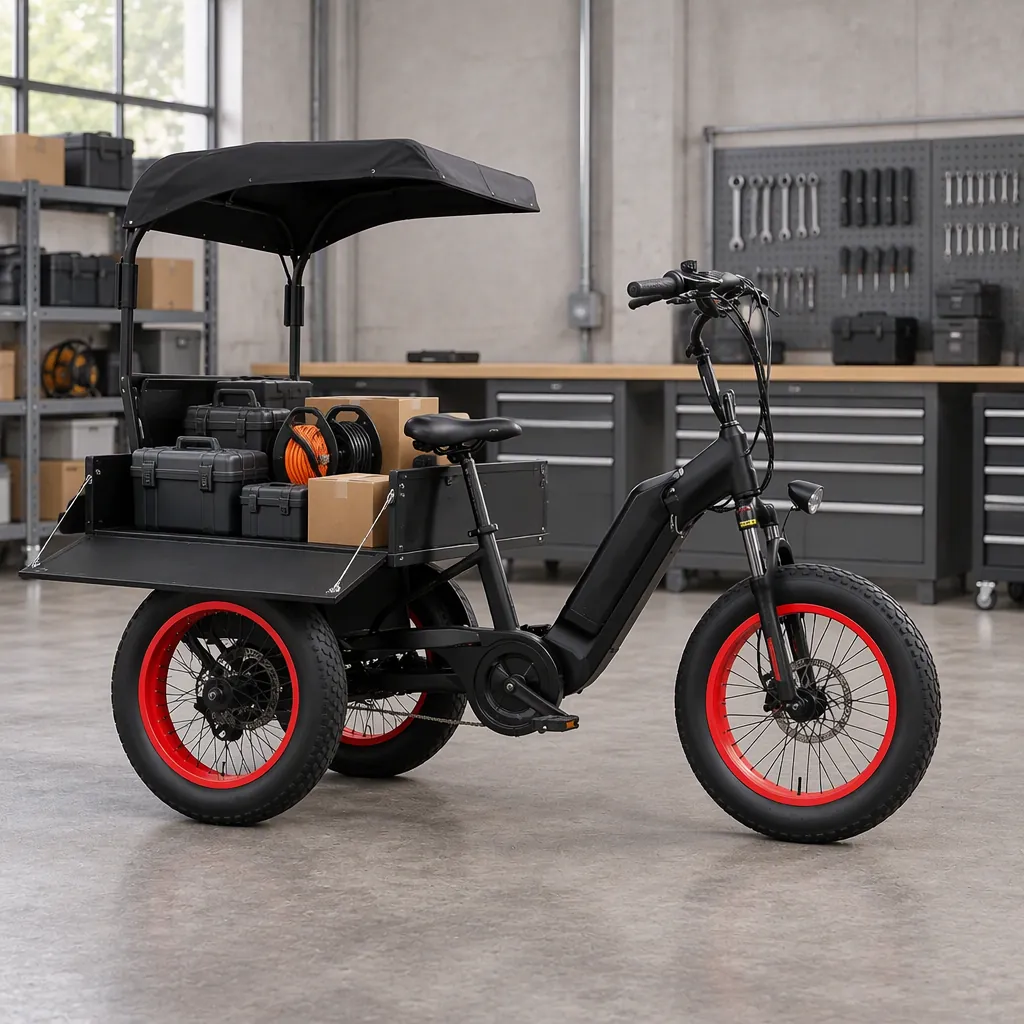
Platform Tiers: Specifying by Duty Rather Than by Price
Operators within one network will have different duty cycles, and supplying them all from a single build is how a program ends up with either over-specified light-duty fleets or under-specified heavy ones. Grade the platform against the job the operator actually sells, using the factory's own build levels.
| Program tier | Drivetrain and pack | Payload / box | Typical operator duty | FOB band (base config) |
|---|---|---|---|---|
| Light urban | 800 W geared hub, 60 V 32 Ah | 300 kg EU rating, 150 L drop-side | Short-hop parcel micro-depots, campus loops, last-block transfer | $1,250–1,550 |
| Standard commercial | 1000 W hub with differential, 60 V 32 Ah | 300 kg EU / 500 kg non-EU, 150–500 L | District parcel and grocery runs, commercial laundry, market supply | $1,580–1,880 |
| Heavy / heavy-duty corridor | 1200 W hub with differential, 72 V 40 Ah LFP | 500 kg non-EU, up to 500 L | Construction supply, waste and greenery routes, incline-heavy districts | $1,880–2,250 |
Two specification notes that matter more in operator hands than in a single-site fleet. First, the standard build carries a hydraulic disc brake at the front with twin drum brakes and a parking brake at the rear on 3.00-12 front and 3.75-12 dual rear tyres — a two-pot rear brake is the first thing to feel inadequate when an operator loads to the top of the range and works a downhill district all day, so reserve capacity belongs in the tier decision; the same brake and tyre wear-outs are covered in the brake system procurement guide and the tyre load-rating guide. Second, the LFP pack on the heavy tier is worth its cost premium in exactly one scenario: districts where units will be charged and discharged twice within the same calendar day. For overnight-only charging the NMC pack is sufficient and the money is better spent on a second battery, as set out in the battery pack selection guide.
Brand and Standards: What the Supplier Actually Supplies
A franchise only works if a customer in one city recognises the same promise in another, and that means the supplier's deliverable is not a vehicle but a set of repeatable assets. Write these into the agreement as named items, because each one is a line item that has to be produced, shipped and updated.
- Livery and decal kit per unit at a specified size, with application drawings and a replacement policy for damaged panels. Box graphics are applied at build and are the reason custom box work adds roughly ten days to a standard 15–30 day lead time.
- Operator manual covering daily pre-shift checks, the charging routine for the pack supplied, consumable inspection intervals for the 3.00-12 and 3.75-12 tyres, and the fault-reporting path back to the supplier's engineering desk.
- Spare-parts kit sized to the cohort rather than the unit: brake pads, inner tubes, a controller and a charger per cluster of vehicles, plus the documented wear items. A parts pipeline that assumes next-day air freight from origin is not a parts pipeline.
- Launch and service training with the operator's first technicians, delivered either at origin or on site, covering drivetrain diagnosis on the differential-equipped rear axle, brake adjustment and pack handling.
- Consumables framework with agreed pricing and lead times so a second-year spares order does not have to be renegotiated from scratch.
None of these depend on the operator's scale, which is the point: they are the fixed overhead of the program, and they are what a prospective operator is actually buying when they sign territory. A supplier that will ship vehicles but not manuals, kits and training is selling a dealership with a different label. The parts pipeline deserves its own scrutiny, because a network is only as good as its slowest resupply route — see the after-sales and spare parts pipeline guide for how the wear-item schedule is structured at platform level and the dealer and distributor program guide for how the same pipeline is specified for a reseller rather than an operator.
Commercial Terms Worth Negotiating Explicitly
Operator agreements live or die on clauses that are boring individually and decisive collectively. The following are the ones worth writing down rather than leaving to the standard export contract.
| Clause | Why it matters to the operator | Factory position to expect |
|---|---|---|
| Territory exclusivity condition | Without it, a second operator in the same district destroys both unit economics | Exclusivity is normally earned by performance, not granted at signing |
| Minimum first order | Sets the operator's real entry cost | 50 units at platform level; a pilot configuration may be possible below that on separate terms |
| Lead time and configuration lock | Determines whether the operator can hit a season | 15–30 days standard; branded or custom box work adds about 10 days; configuration locks at order |
| Spares pricing horizon | Second-year operating cost is dominated by parts | Framework pricing with a stated review interval rather than open-market repricing |
| Resupply priority in peak season | An operator who cannot replace a write-off mid-season loses the territory | Named allocation for network operators ahead of open-market orders |
| Data and telemetry ownership | Decides who can use the fleet's operating data at contract end | Should be written even when neither party intends to use it in year one |
Where This Fits Alongside the Rest of the Channel
Operator programs rarely replace a dealer network; they sit on top of one and change what the dealer sells. The pattern that works is sequential rather than parallel: a dealer proves the product moves in a market, an operator then proves it can be run as a service in one district, and only after that does a branded network make sense across a region. Importers weighing an operator program against a dealer appointment should read the unit-economics section above as the deciding evidence — if the local demand cannot support forty billable vehicle-hours per month per unit, a dealer network is the correct structure and an operator program will simply produce an early failure that is harder to replace than a missed appointment. Two adjacent models are worth reading next to this one: the two-wheel rental fleet guide, which covers a single operator running its own sites rather than franchising them out, and the guided tour operator guide, which is the narrowest and most seasonal version of the operator role.
How many operators should a first cohort have?
Two or three districts, not ten. The first cohort is where the manual, the spares kit and the training are tested, and every one of those assets gets rewritten once real operators use it. A program that signs ten districts from an untested kit spends its first year managing complaints instead of expanding, and the districts that fail are the ones it can least afford to lose.
What does the operator own at the end of the term?
Under a straight purchase, the vehicles and any branding applied to them. Under a lease or placement structure, this has to be specified precisely — which is why the ownership table earlier in this page matters. The clause that causes disputes is not the vehicles but the branding and the customer relationships, so state explicitly whether decals are removed, retained or bought out at term end.
Can one territory run more than one platform tier?
Yes, and most successful districts do. A commercial district typically starts on the light urban tier for short hops and adds standard commercial units as the operator wins longer routes, rather than buying the heavy tier up front and running it half-loaded. Mixing tiers within one fleet is normal; mixing tiers without separate spares planning is not.
What is the first thing a prospective operator should measure?
The number of hours per day a vehicle could realistically be occupied in their district, not the number of enquiries they receive. Enquiry volume tells an operator how much demand exists; occupied hours tell them whether that demand is dense enough to pay for the fleet. Only the second number decides whether the program is bankable.
How does this differ from a dealer agreement?
A dealer is measured on units moved out of the warehouse and carries no obligation to operate anything. An operator is measured on service delivered inside a defined territory and on the uptime of the vehicles doing it. Everything else — territory clauses, training, spares frameworks and resupply priority — follows from which of those two the agreement actually describes.
Next Step
Before signing any operator, map the district: the furthest point from the operator's base, the density of the trips you expect to serve, the lockable overnight charging location and the single jurisdiction the territory sits inside. Those four answers determine the platform tier and the unit count before price is discussed, and they are also the four numbers a leasing partner will ask for. Send them with your target city list and expected services, and you will receive a territory map, a recommended platform mix per district, a spares and training kit specification and FOB indication for a first cohort — plus a pilot plan for the strongest single district.
Build a District Operator Network
Tell us your target cities, units per location and the services your operators will sell. We will map the platform tier, recommended unit count, spare-parts kit, branding package and the commercial terms for your first cohort of districts.
